Personal Journal: the strategic default of the house we purchased in 2006

Thursday, March 18, 2010

Why I'll Miss My Home


Spring
I'll miss my home because of spring.

I won't miss a realtor leaving the key in an unlocked door today, unnecessarily exposing my house to the random drive-by rubberneckers, robbers and dog-nappers.

P.S.  You can't smell this tree just from a photo, which is such a shame.

Wednesday, March 17, 2010

Short Sale Taxes

It's tax season, and taxes are on my mind.  I think taxes are super boring, and sometimes terrible.  Before we decided to sell our house for less than we owe, we went to a real estate lawyer.  It was our hope to avoid any potentially terrible/taxable/illegal things happening that we were not ready for.  We wanted to be informed.


If we short sell our house, the difference between what we owe, and what the buyer pays is potentially and usually taxable by the federal and state governments.  This seems silly as we would never see the cash, but it is because the government sees the difference as a 'gift' from the lender.  It would be a gift to be out from under an extravagant loan.

Fortunately, George Bush made a federal tax shelter on short sale income until December 2010.  The state can tax the difference if the house is not your primary residence and you have lived in it less than 2 years.  It seems as if we are in the clear on the tax front, but nothing is a sure thing.

If we are taxed on the difference, the tax will be negligible compared to the extreme cost of the loan and house we currently live in over the lifetime of the loan, or until we could sell and make money (in 37 yrs. looking at statistics).  We are having faith that this might work out, and by faith, I mean faith with a lawyer as an angel.

Tuesday, March 16, 2010

Short Sale Sob Story


Here is the latest on the short sale.  There is no news.

Though the price of our house dropped $40,000 last week, and more than 8 groups of realtors and potential buyer cruised through my immaculate house (opening my closets!!) over the weekend, no offers.

In 2 weeks the price will drop again, and it will stop dropping there, I hope.  The irony here is the lower the price, the more folks come to see the joint, and the less I want to keep it clean.  Taking excellent care of something that is worth so much less than we paid is disheartening.  Also, the lower the price goes, the less likely the bank will approve of a short sale.  They want the money we owe them, and at this point, it will be a big gap they would forgive.

Today, I threw the bag I carried on my bike ride on the counter along with the mail, all the dishes are undone, and 5 days worth of clean laundry is on the couch.  I have not vacuumed in 3 days (my vacuum broke).  If a realtor calls to show it, I'll just say no.  It kinda seems that it doesn't matter.

On an up note, the longer we stay in our house, the more likely my veggies will be mine at the end of the summer.  90 days of a short sale from now would be mid-June!  A few more weeks out, and I have tomatoes in August.

Monday, March 15, 2010

Mortgage Weight Gain

Talking about your mortgage is in an area of taboo topics. The others include bathroom and bedroom habits, personal salaries and weight.  The World Wide Web is rife with taboo topics, so this post fits perfectly.  I know banking and real estate are big business, but my house is personal.  I'll pick the lesser personal topic as an analogy of my mortgage.

We need to eat, just as we need shelter.  Could you imagine if you sat down to an average, everyday breakfast, nothing fancy, just fuel to keep yourself going during the day, but there was something amiss?

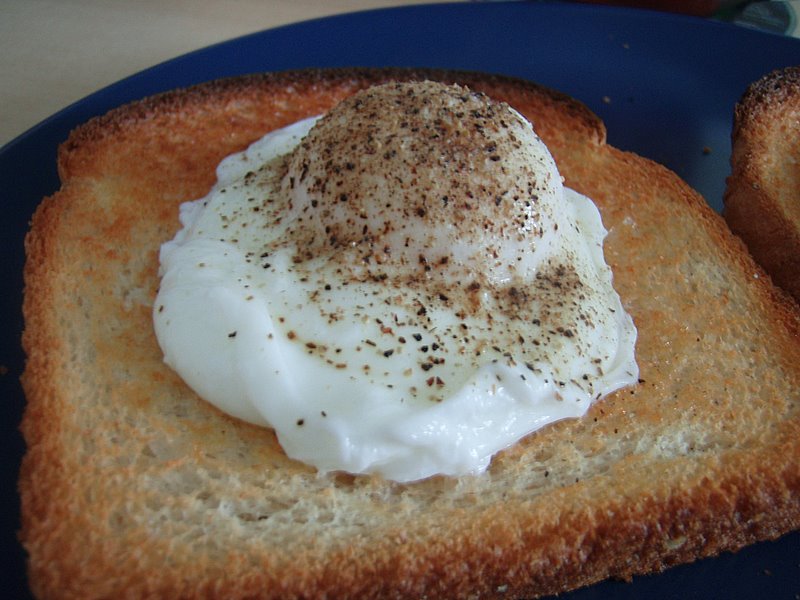
It looks like a piece of toast and and egg, but you have this nagging feeling.  You have been eating this breakfast everyday for 4 years.  It is healthy, it has whole grains, protein, and you need it.  It is high in fiber, just enough fat, and seemingly, the right amount to get you to lunch.

Contributing to your doubts are 50lbs you have gained in the last 4 years.  Though this reasonable meal seem perfect, what should have 350 calories, really has 2,000 calories.  You don't feel any fuller, but the scale, and your waistline tell you differently.  The toast and egg people are telling you to eat it anyway saying you can lose the weight in 40 years.

This is a perfect analogy of me and my mortgage.  I am a sensible and reasonable person in most areas of my life, especially those 'unmentionable' areas.  Paying for this house, is thinking you are eating diet food, and actually eating everything on the McMenu.

Though the 7-8 groups of potential buyers that walked through my house this weekend made me grieve the loss of this house, I also want to get my diet back in check so that I am not a 70 year old, sick homeowner.

Friday, March 12, 2010

Rhetorical Mediocrity

I've read mediocre books where at some point in the story, the author or editor spoon feeds the reader, rather than just tell a great story.  The main character starts to ask rhetorical questions of himself such as, "Does she really love me?  How long is it going to last this time?  Should I buy a loaf of bread?" so that the reader can get into the head of the character.  It is a cheap trick, or at least I think it is, I'm not an author.  Needless to say, at this point in any book I'm frustrated!

Today as I scrubbed my kitchen for potential buyers, mopped, dusted, folded, and de-cluttered for the 30th time in as many days, I find myself asking silly questions to keep the story going, or to keep the house clean enough for perfect strangers to tromp their muddy shoes through.

"Why am I cleaning my house so much when no one really cares?  Why do I care what anyone thinks of how I keep my house, or me for that matter?  Why can't I just relax all the way about this house thing?  How did Malt-O-Meal get here?"

With the feather duster in hand this morning, I decided just to tell the story (and keep cleaning).

Also, a huge thank you to my talented friend PR Frank http://prfrank.com/ for making me a banner, so I can feel like a real blogger.

Thursday, March 11, 2010

Escrow Account


I can't think of anyway to embellish the details of our escrow account.   Tax laws, interest rates and escrow are technical details that I have trouble bringing to life with words.  Let me give it a try anyway.

I called to get the money out of our escrow account the day I also turned off the not-so-easy-pay for our mortgage payment.  An escrow account is a holding tank for money that gets used for things other than paying for the house, such as insurance and taxes.  We have to keep a lot of money in the account, as our house is very expensive.

I wanted the money in the escrow account so that I could pay my taxes and insurance, in fear that the lender would use the money to pay my mortgage, or as 1/1000 of a bonus for Vikram Pandit, the CEO of Citigroup. 

Here is the deal on getting money out of escrow accounts at Citi:  If you are current on your payment, then you can get the money out.  At the time I called, I was current, but we all know how that turned out.  You can also get the money out of escrow if your house is worth 75% of what you owe on the house (loan to value ratio).  Clearly they are worried that folks like me, whose loan to value ration is 63% are a risk.

A person with a loan to value ratio of 63% might decide it is silly to pay the mortgage and want the cash out of her account.  They offered to snail-mail me some forms within 10 business days (which is really 2 weeks).  The form did arrive 2 weeks later, and it had more information on it than the lady on the phone told me, that bit about the loan to value ratio, she forgot to mention, or at least I'm letting her 'forget'.

Can I interest you in some tax law tomorrow?

Wednesday, March 10, 2010

Two Camps


Since I started writing this blog last Monday, it has stirred up some conversation/controversy.  I opened myself up for the conversation, and am having them at the park, in the pick-up line at school, at the grocery, on the phone, on Facebook, and at the dinner table.  There are basically two camps of folks.  

The first group are unsure of our plan.  I hope this is out of concern for our welfare and safety, as well as not knowing the preparation we put into our decision.  

The second group are curious, or have already gone through something similar.  I have heard dozens of stories about all the trouble people have gone through on behalf of their houses.

Let me assure the unsure.  We have sussed out the details as best as anyone can.  We've considered the taxes, the lender, the relator, our financial well-being, our children's college accounts, the law, our consciences.  When we do the numbers, and consider our options, we are sleeping well at night.

For those of you who have gone before us, I welcome your stories.  I can only learn from anything that you have already experienced.

Here is a book that Silas and I read, that really helped us, in an all-around kinda way.