Personal Journal: the strategic default of the house we purchased in 2006

Tuesday, April 27, 2010

I Love Citi!


Subject: BROWN SS APPROVAL 124 DEER PARK


MAKE SURE FULL ARMS LENGTH, FINAL SIGNED HUD AND WIRE CONFIRMATION COME
STRAIGHT TO ME UPON CLOSING TO EMAIL OR FAX 866 421 4408

I know that my frustration with my inability to break through to some sort of resolution personally with Citimortgage might have jaded my former posts. With a lot of help from an experienced realtor, a patient buyer, and a full moon, we received some good news today.

Chatting with an old friend (he was kind), I was struck at how jaded and judgmental I was feeling towards an institution. What a waste of time. Today I am grateful that Citi didn't take its time approving our short sale. We will move by June 4th, unless something changes. Nothing is a sure thing.

It is amazing how one can be lead by her feelings!   Today, I feel fine, like I weathered a small storm. Thinking about it, nothing has changed.

Now, to find some boxes, a place to live, and a new plan.

Monday, April 19, 2010

I'm Super Helpful


I have been researching the state of real estate, for this blog, and to squelch my ignorance on the subject.  There are so many differing opinions.  One day I'm sure that the dire situation of our nation is directly because Silas and Tyson stopped paying our mortgage (your house is worth less because mine is being short-sale-d, the lender won't talk to you cause I'm on hold on the other line, I don't have a hardship, the stock market is down because I have a toxic loan with Citi).  Then the next day I'll read something strictly the opposite!  Let me explain the latter.


Consumer spending is up. Consumer spending is the driving force of our economy.  This is seemingly positive news.  You can read that article here.  Unemployment is up, savings is at an all-time low, consumer debt is at an all-time high, millions of home owners are in foreclosure, and millions more are delinquent on the mortgage or underwater.  Why are more people buying more stuff, if things are getting worse?  The claim is that freed-up cash from delinquent mortgage payments are making their way to the cash register.


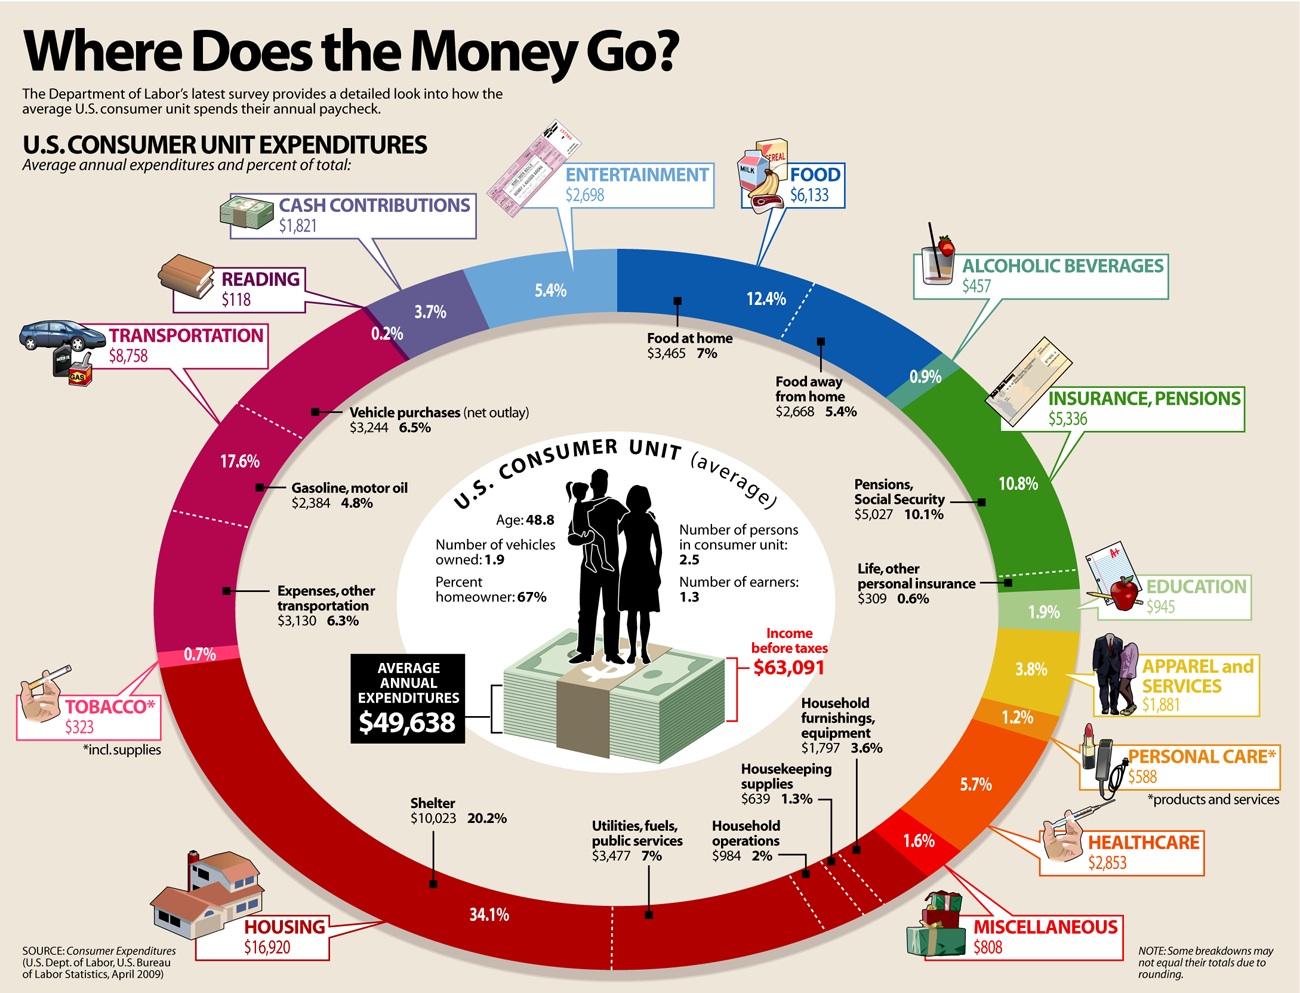
Consumer spending is a HUGE part of our economy.  It actually hurts my head to think that upwards of 72% of our economy is used on buying stuff.  Consumer spending is the discretionary money people used on discretionary things.  They are: clothing, electronics, recreation, household goods, alcohol.  I'll bet you have already figured that we spend the most of any country.  This is a chart to see how we rate compared to others.  Most people in the world have to spend most of the money they earn on housing, food, and health care.  We are fortunate to have the luxury of so much extra.  We have made our luxury a driving force for our system of stability.  I digress, on to how helpful I really am....


I really like being a helpful and useful person.  It is satisfying, and who I am. At the same time, I'll admit I don't buy much stuff.  I'm super frugal.  Even if I have money, I don't want to spend it, or don't want the stuff you can get with money.  I am sure I don't spend 72% of our budget on consumer goods (positive, actually).  I'll admit it might even be a problem for me.  Sometimes I don't buy something I need, because I am (I'll just say it) cheap.  The only exception is if I can spend money on someone else, I'll make an exception for you.  Could spending money be useful, or even benevolent?

In the past week I realized that spending money we aren't paying for our mortgage, might free us from 'economy-wrecker-purgatory'.

So far, since we stopped paying our mortgage, I have bought several things.  I'm now wondering if I did it because I have some extra money.  Did I buy a few extras because I knew it wouldn't impact my budget?  I'll list the consumer things I got: 3 new shirts, 1 pair of shorts, pants for my husband, summer sandals for my kids, 4 movie tickets during spring break.   I scour for the 75% off stuff (and no, not 75% off at Neiman Marcus) and try to get only what we need (need being relative).  Maybe we went out to eat 5 times extra since we stopped paying, but mostly we eat at home.  Maybe I got those sandals a month earlier than usual from Ross.  Maybe I wouldn't have taken my kids to the 3-D movie. 

I guess all I have to say is: 
Your Welcome

P.S.   Please know that this is in jest.  I understand that so many are really suffering from the demise of our economy, real people with children, and bills.  I think it is despicable that spending cash on expendables could bolster economic indicators and make us feels as if we are all 'okay'.  I still see so many out of work, and living on credit cards, and losing their house.   The irony of this is that we feel we are collectively helping, by buying an MP3 player and an extra six pack.

Friday, April 16, 2010

Catching Up

I went out of town for a week, and didn't blog, and tried to think about other things for a bit.

After 3 month on the market so far, and 50 realtor visits, someone made an offer on our house today.  Also, foreclosure proceedings should start soon, as we will be 90 days late in a few days.  It is a race to see if we can short sale our house, or the bank will foreclose.  We are skeptical that we will be able to short sale our house, as we are in no need.  The bank will have the final say.

An offer gives us a time line:  90ish days.  I hope the folks who made the offer have the patience of Job, and don't mind being disappointed if the bank declines.  If they can stand the heat, they will have a value-price dwelling!

I'm excited to think of renting as I am up for a change.  A friend even offered me a plot in her garden, so I can still have that!  I am trying to have hope and integrity.  An offer, or even any sort of movement makes that easier.

The news has been FULL of reports about our situation, and others like us.  Here is a clip from a morning show.  It is kinda a downer, so think about a cool trip to the zoo when you were a kid after you are done.  Let's not take ourselves too seriously.


I don't have TV, but folks are passing stuff my way.   Thanks so much!

Tuesday, April 6, 2010

I Lost on Jeopardy

I have been learning more than I ever thought I would about the world of real estate, lending, and borrowing.  As I have previously posted, what I have learned up to this point is nearly nothing, compared to the vast amount of knowledge there is to know.

The other day, my dad was talking about derivatives which is not real estate, but finance.  At some point all roads lead to finance, but I'm still confused about how real estate and finance connect (one thing at a time).  It is not important to know what derivatives are for this post, because his point is that you can count on one hand the folks who actually know what one is. (Knock yerself out at Wikipedia just to get a taste of the confusion).

I feel as if all the details there are to know about strategically defaulting on a home loan and influencing factors, is like trying to know about derivatives.  There are just so many details it is nearly a mystery.  I am trying to break it down for myself, because unlike derivatives (I think), this real estate stuff affects me.

So what is the difference between not paying my credit card debt, and not paying for my home loan?  This is something that we have had to grapple with, since we pay one, and not the other.  Like on Jeopardy, the answer is in the question.  One is consumer debt, and the other is real estate.

When I buy dinner out, or a stereo for my car with consumer credit, I've done just that, used something up. I have consumed it.  The burrito I ate 9 months ago and paid with credit, as with my stereo, are no longer of value.  The credit card company, for a price, will pay for me, until I can pay.  They do not care about the burrito after they have paid for it.  It does not have any value for me or them.  The value for the consumer is that if you want or need something now, you can pay more later.  The value for the credit company is that they, for the most part, take money hand-over-fist.

Real Estate is a bit different.  It is REAL.  When people get a loan for a house, the house itself is collateral.  It secures the loan and the signed contract sets the property as being equal to repayment of the loan (well even normally the loan is for 80% of the value of the house.. ensuring the bank can always get its value out of the property).  This is why there even exists such an option as foreclosure.  It is essentially a legal pathway to resolve the differences between a homeowners willingness/ability to pay, and the banks desire to get paid.  With consumer debt the bank "invests" in the individual, in the case of a home loan, the bank shares the risk in the collateral.  This is supposed to mean that when the property decreases in value because of the market, the bank should be just as motivated to solve the problem and keep the property afloat as the homeowner is...but because most of us think that we should keep paying out of our desire to be faithful people...the bank can afford to stall.

We have a contract, for my house, with Citi.  It is like a triangle, three sides:  lender, borrower, structure.  If Citi decides they want out of the contract, with my permission, they can give me the house.  If I want out of the contract, with permission, I could give them the deed in lieu of payment.

At this point, both Citi, and Tyson have lost money on this house because we have a contract together.  These are strange times.  It is strange that our home is a "black hole asset".  I am not going to pay for an asset, that by all accounts, will never be an investment.  I have the ability to give the real thing I am not paying for, to Citi.

I know that even my explanation of the situation is probably up for interpretation, or even wrong.  Like I said, I am just learning about something that is exceedingly confusing.  A blog is a pretty communal place, so let me know what you think.  Set me straight.  Let's let Citi worry about what a derivative is.

Thursday, April 1, 2010

Reproduction vs. Debt Reduction

Last night, a representative from Citi called us at 8:15pm and didn't hang up.  I arrived home to a calm husband, having a rational conversation with someone on the phone.  I thought it was his mom, but no, it was 'Home Owner's Assistance Dept'.  Here is what I heard my husband saying on the phone,
Well, it seems that you guys have the ability to help us figure out a modification, or principle reduction, so what ever happens next, it is up to you.
What a change, not our calm-ness, but the person on the phone was seemingly helpful.  They did transfer him a few times, but in the end, there were more results when they call you, and not vice versa. If you call them, they can not help you.  If you call them and are paying your mortgage, they really can not help you.  Waiting for them to call you is hard.

We have now submitted a loan modification form that will help us be assigned a 'mortgage counselor', even though the modification they have in mind is useless to us.  This is help from the inside, instead of David cracking the egg of Goliath from the outside. Maybe they will be more helpful if there is one person, who is not haggard from the 4 million stories of despair and suffering from the borrowers.  I can pay my mortgage, so I can be calm and at ease on the phone, but many are jobless, have children dying of cancer, as well as losing their homes.  I can see that the gatekeepers at Citimortgage have to be callused individuals, and continue everyday with gate-keeping.  What a tough job!

The mystery of the mortgage industry, is much like the mystery of reproduction.  It is a learning process that, though shrouded in mystery, can end in understanding (and pain).  Though human reproduction is mysterious and miraculous, the mortgage industry is just expansive and mysterious.  In that way, the similarities end.

When I was very young, I was very confused about sex and reproduction.  I was clueless to its existence.  It was as if my mom just kept bringing home new people to live with us, and I had no idea how it was happening.  As I grew older, I learned more about the world and realized how a baby made its way into the world: it came out of women's belly-buttons (who didn't think that was how it worked for just a minute or two?).

As I grew even older, I became informed via the usual pubescent ways (I won't explain, my mom reads this).  Then I got married, and learned more, culminating at 23 years old,  and the moment my son was born.  At that point, I'd come a long way from the pre-schooler I was 20 years beforehand.

As I have been negotiating with Citimortgage, I have determined my understanding of the situation is nearly like my understanding of human sexuality and reproduction (though less rewarding and fun by a LONG stretch).  It is something to be learned about by experience, and from the inside-out.

I think that I might be age 6 in my development, having just learned that there is such a thing as a mortgage company, and suspicious there is more too it than I thought, just a few years ago.

Tuesday, March 30, 2010

The Details of Hope

Here are some details that we have to consider as the federal government continues to try to bail out the real estate market.

Some of the programs may apply to us.  Making Homes Affordable is a program that our lender is participating in.  We could lower our monthly payment to 31% of our income.  We were not crazy when we bought this house, and spend 32% (still in my opinion, high, but it was what a house cost).  Citi offered to lower our payment through refinancing by 1% of our monthly income, saving us close to nothing over the lifetime of our loan, as they were also willing to charge the going rate for a refi.  In several years we could have recouped the cost of modifying our loan using Make Homes Affordable, which in the end, doesn't really make our house any more affordable.

So far, the Make Homes Affordable project has helped 170,000 home owners.  This is wonderful news for those home owners.  The project was anticipated to be viable for 3-4 MILLION home owners initially.  People with more expertise than me, are estimating that 5% of the 3 millions folks will actually get a loan modification using this program.  I actually could be one of those 170,000 homeowners, but it wasn't a savings for us.

This is why last week I was a bit excited about new programs being formed to help even more underwater and unemployed home owners.  There are many details.  The main deal is that we would need to get current to salvage our credit score.  In the case that we did get current, our principle could be reduced 15% per year we have been paying.  This is equal to the dive the market took.  It would make our house affordable.

After the excitement of the new announcement wore off, I started thinking.  Which federal assistance program adopted in the last 2 years has been really effective?  Which one has offered real assistance to me, my neighbors, small businesses, corporations, the stock market, etc.  If we were able to participate, or our lender is participating, the only difference between a federally funded principle reduction and a short-sale, would be my credit score, the taxes owed to the state of California, and my proximity.  Are those things that I want to leave in the hands of the government and the lender?  Do I really want to wait and hope on these institutions to resolve the situation?

For now, my answer is no.  I'll jump through their hoops if they put them out for me, but the track record is pretty bad.

Monday, March 29, 2010

Beauty and the Beast: The Last Rose Petal


I got a rose as a gift several years ago.  I put it in a pot, and not the ground because I have trouble committing.  It blooms dozens of tiny brilliant roses.  Some summers I can get it to bloom twice.  Early this year I moved it indoors to our garden room.  It pushed out, and then thousands of aphids attacked.  I started killing those little killers with glycerine, and soap, and bodily pulling them off.  There were too many to get rid of, and the photo you see proves it.  They really devastated the whole plant (it is not exactly dead).  I put a lot of time and effort into what was once a beautiful plant.


I have another rose nearby, and it is pest-free, and blooming.  Asking advice from a friend, he said something that I had forgotten in my forceful attempt to kill the pests.  If aphids are only attacking one plant, then the plant is compromised in some other way and the bugs are just responding.  Another example is the lion killing the sick wildebeest, and the  healthy ones escape.  It seems a natural order.  For some reason I thought I was independent from the natural order.


My friend's advice gave me permission to take the rose out of the pot, and put a healthy one in.  My usual way, is to work, and work, and work, even if the results are bad.  Sometimes I can do this ad nauseam.  I also need to point out, that some things are worth working yourself to death for, but most are not.  I am learning the difference.


When I took the rose out and looked carefully, the roots were moldy.  I could have continued on my path, but in the end the pests weren't the problem.  I pruned the rose back to the quick, dug it a new hole, filled it with compost, and put the plant in the readied hole.  It was 5 times easier than picking off the aphids one-by-one.  It still may not survive, but at least it has some chance. 

In relation to my mortgage and housing situation:
If I do nothing but what I'm doing until I'm 60 I'll own this house.  Though things are excellent now, life is dynamic.  If ANYTHING changes for us we will be stuck tending what was once a beautiful thing.  By 'stuck', I  mean trapped.  I doubt  my life will continue on just as it is for the next 30 years.  Let's look at some reasonable scenarios that I am stuck with in case of life altering events, such as moving, job changes, home upkeep and repair,  illness, college tuition, California falling into the Pacific ( I threw that last one in to see if you were paying attention).  If the real-estate market had continued to be a profitable venture after we bought our house, none of these would influence us so radically.  Just imagine:

I might have to move in the next 30 years before I have paid off my house, but alas, I would not be willing.  If we did move we would have to pay for this house, and pay to live in another, because I would NEVER sell this house for a profit.  I would never sell my house and give the lender the difference.  
I would be so opposed to selling short or foreclosing that I would pay no matter what.  I would be so opposed to paying for 2 houses, that I would never move, and I would pressure my husband to make a huge salary, or find a bad job at high pay, even if he is miserable, so that I would not have to sell short or move.  
I could lay awake at night and worry about my young handsome husband dying early.  Not because I love him dearly and would miss his pun-ny jokes, but because without his salary, I could not live in this house.  Because of when we bought our house, we have to live in this house.  
I could imagine myself getting a job teaching school to make the mortgage at all costs, and then I think of more that 20,000 more qualified teachers than myself, being laid off by the state of California just this month.  Every one of those teachers has a story just like mine, they have a family, and a mortgage too!  Even if I did get a teaching job, and I have this modest house, a teacher salary would not pay the mortgage.  I could get a job in another field, but I have no skills, as I have been tending to my children for the last 10 years, so I would have to go to a University.  We don't have a university in our town (which I HAVE to live in) and I have maxed out my community college credit limit, so I would have to drive to Sacramento, or do classes on line.  That is do-able, but not when the first of the month just keeps coming, my husband is miserable, my kids are nearing high school graduation and college tuition themselves.
I have had to change.  I have had to stop pushing ahead without results.  I have had to stop feeling under the influence of hard economic times, as a victim.  I have had to stop actually caring about what everyone thinks.  I've stopped worrying (for the most part) that people will see my 'pests', and in the end the plant will die regardless of my actions.  I have had to stop being distracted by the symptoms of the problem, and reviewed the cause.  As it turns out, I have little influence on both.


I guess I have decided not to do that to myself, and my family.  I choose not to be trapped when I can, not to be afraid, and not wait for that last petal to fall off a dying rosebush.  I choose to love my husband for who he is, not for what he can do for me.  I know that terrible things will happen to me in-which I have no choice.  I choose for my house not to be one of them.  I think now is the time for damage control.